You are covered by your own policy, through uninsured automobile coverage
An uninsured at-fault driver does not leave you stranded. Ontario requires every auto policy to include uninsured automobile coverage, and part of what it does is pay for damage to your vehicle when the driver who caused it is identified and has no valid insurance. It sits alongside DCPD on your own policy: DCPD is the usual route when the other driver is insured, and the uninsured automobile coverage is what steps in when they are not.
There is normally a deductible on that coverage, and it can differ from your collision deductible. Check the declaration page. If you also carry collision coverage, the adjuster may run the claim under whichever coverage serves you better, and you can ask which one is being used and why.
What the coverage needs from you is a clear record that the other driver was at fault and that the vehicle and driver were identified. That is why the next hour after the collision matters so much.
What to do at the scene when the other driver cannot show insurance
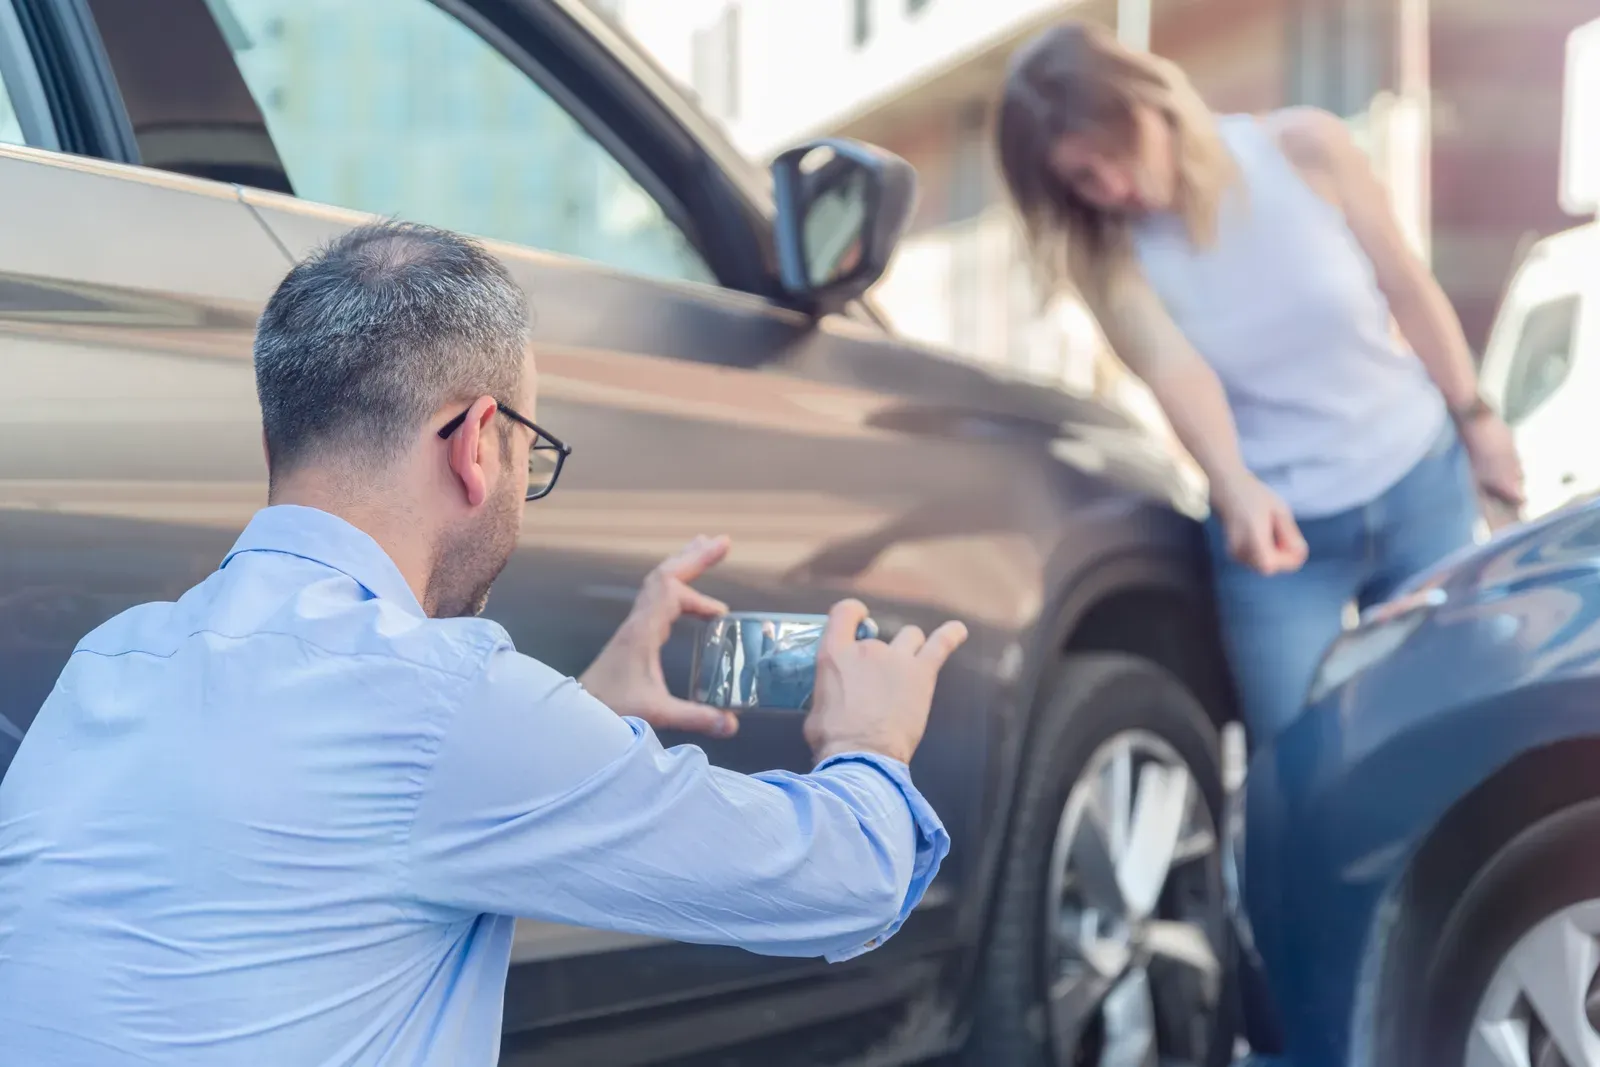
Get the driver’s name, licence number, plate and a photo of the vehicle, and do not accept a promise to pay privately. A driver with no insurance is facing heavy fines and a possible suspension in Ontario, so there is every incentive for them to talk you out of reporting it. Be polite and report anyway.
Involve the police. Driving without insurance is an offence, and a police or Collision Reporting Centre report that records the missing insurance is the document your claim will lean on. In Toronto, the nearest Collision Reporting Centre will take the report if the police do not attend. Photograph the scene, the damage to both cars and the other driver’s plate before anyone leaves.
Then call your own insurance company, within the seven days the policy expects and preferably the same day. Tell the adjuster plainly that the other driver appears to be uninsured. That single fact routes the claim to the right coverage from the start.
Can you go after the uninsured driver directly?
Yes, and it is rarely worth it on its own. You have two years under Ontario’s limitation rules to sue for property damage, and a driver who could not afford insurance is often a driver who cannot pay a judgment either. The practical path is to claim on your own policy, let the insurance company pursue the at-fault driver for what it paid, and keep your own paperwork in case the recovery ever affects your deductible.
If the insurance company recovers its costs from the uninsured driver, ask whether your deductible is returned. That happens sometimes. It is not guaranteed and it can take a long time, so plan as though the deductible is gone.
Keep a file from the first day. The items below are what the adjuster will ask for, and what a small claims court would ask for if it ever came to that.
- The police or Collision Reporting Centre report number, and the officer or centre that took it.
- Photos of the other driver’s plate, licence and any insurance slip they showed you, expired or not.
- Your own photos of both cars at the scene, before anyone moved.
- The estimate, supplements and final invoice from the shop.
- Names and contact details of any witnesses, with a line on what they saw.
- Every email and letter from the adjuster, including the coverage the claim was paid under.
The repair does not change, only the paperwork does
Nothing about the physical repair depends on the other driver’s insurance. You still choose the shop, we still write the estimate from your photos, and we still deal with the adjuster on supplements and parts. The only difference on our side is the coverage name on the claim, and we confirm that with the adjuster before the car goes into the booth.
A rental is the one area where it can differ. Loss of use under an uninsured automobile claim depends on your policy wording and whether you carry OPCF 20, so ask early rather than assuming the rental will be there.
If the car is not drivable, have it towed here rather than to a yard. Ontario leaves the destination of a tow to the owner, and a car that lands at the shop that will fix it avoids a second move and a second storage bill.
What about a driver whose policy lapsed or was cancelled?
From your side, it is the same situation. A cancelled or lapsed policy is no insurance, and your uninsured automobile coverage responds the same way. The insurance company will verify the other driver’s status with the pink slip they showed you, which is why a photo of that slip, even an expired one, is worth taking. It gives the adjuster a policy number to check and a company to chase.
The one thing not to do is let the other driver talk you into waiting while they “sort it out”. Every day of delay makes the police report harder to get and the story easier to change. Report it, claim it, and let the paperwork catch up with them.
Questions people ask
Will a claim under uninsured automobile coverage count against me?
It is a not-at-fault claim on your file. How your insurance company treats it at renewal is its own question; the page on whether a claim raises your rates covers it.
The other driver offered cash to keep it quiet. Should I take it?
No. You will not know the true repair cost until the car is torn down, and a cash promise from an uninsured driver is hard to collect. Report it and let your coverage do its job.
What if I have no collision coverage and the other driver is uninsured?
Uninsured automobile coverage is on every standard Ontario policy, so you still have a route for the damage as long as the driver was identified. Ask the adjuster which coverage applies.
Does this apply if the uninsured driver hit my parked car?
Yes, as long as the driver was identified. If the driver left without stopping, it becomes a hit-and-run claim, which has its own page.